
PARIS INSURANCE AGENCY
Protecting What You’ve Built. Securing What Comes Next.
Trucking Insurance
Property Insurance
Casualty insurance
Trucking Insurance
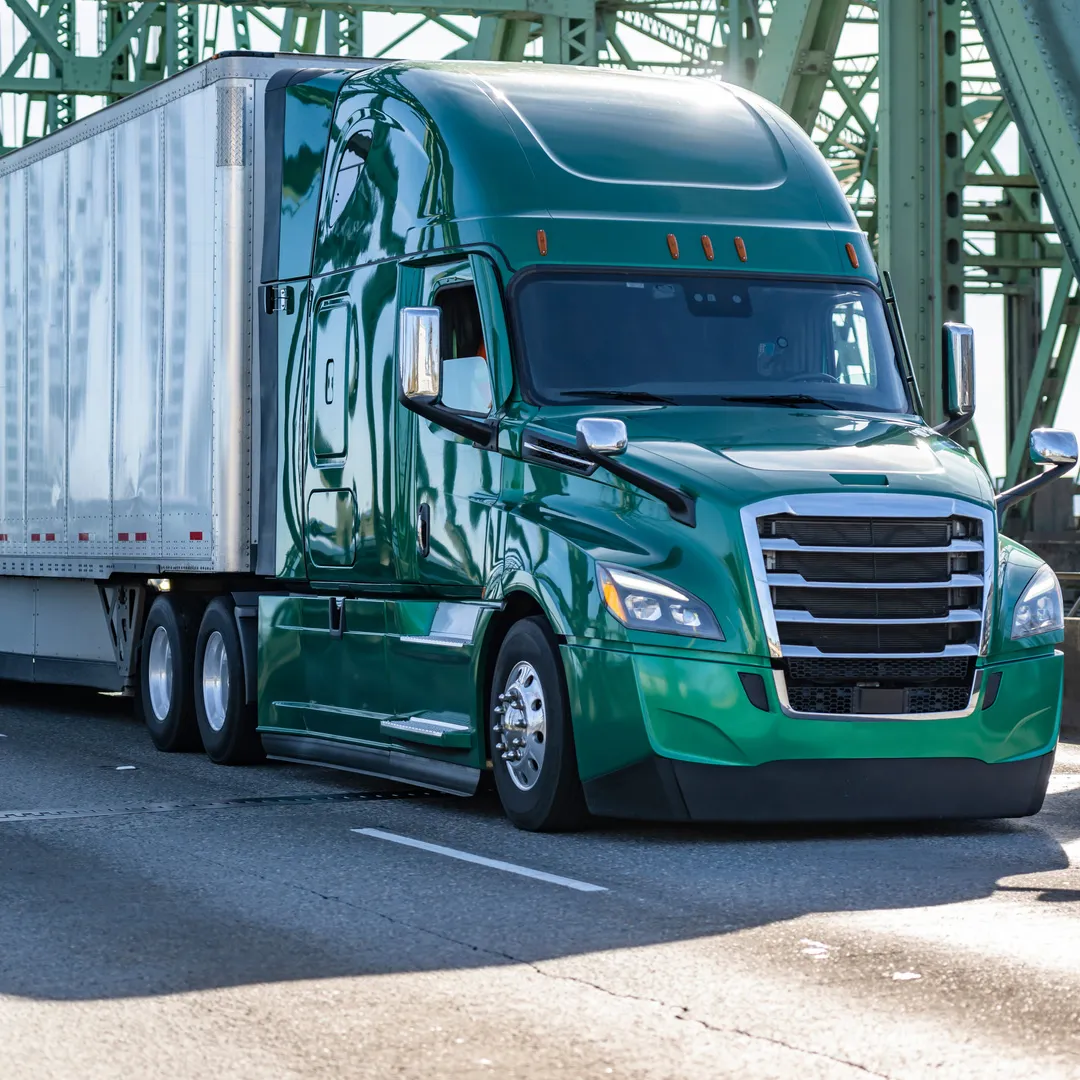
Motor carriers face exposures that a general commercial policy does not address. We place commercial auto liability on your power units, motor truck cargo for the freight in your care, and physical damage on tractors and trailers. Non-trucking liability, often called bobtail, responds when a unit is operated outside dispatch. Trailer interchange covers equipment you pull under a written interchange agreement, and reefer breakdown addresses temperature-controlled loads when refrigeration equipment fails. Excess and umbrella liability sit above the primary limits when a shipper or broker requires higher limits than the underlying policy provides.
We also handle the documents that keep freight moving. That includes certificates of insurance issued to shippers and brokers, additional insured and waiver of subrogation endorsements written to match your contract language, and the insurance filings tied to your MC authority and DOT number. Every placement depends on underwriting review, the carrier's appetite for the risk, and the terms of the policy the carrier issues.
Property Insurance
Commercial property insurance covers buildings you own or lease, along with furniture, inventory, and business personal property inside them. Smaller operations often place a business owner's policy, which combines property and general liability in a single contract rather than two separate ones. Inland marine and equipment coverage follows tools, trailers, and specialized equipment that move between job sites and yards instead of staying at one address. Business interruption replaces lost income and covers continuing expenses when a covered loss shuts an operation down, with the deductible and waiting period set during underwriting.
Premises liability applies to customers, drivers, and vendors who come onto your property. Garagekeepers coverage applies where you take custody of vehicles owned by others, such as a repair shop, tire service, or storage yard. What a carrier is willing to write, and on what terms, is determined through underwriting and stated in the issued policy rather than promised here.
Casualty Insurance
Casualty insurance covers your legal liability when your business causes injury to a person or damage to property belonging to someone else. General liability is the base layer, responding to bodily injury and property damage arising from your premises and your operations. Excess and umbrella liability extends those limits when a customer contract or broker agreement requires more than the primary policy provides. Products and completed operations covers claims that surface after a job is finished or a product leaves your control. Employment practices liability addresses allegations brought by employees, including wrongful termination, discrimination, and harassment. Workers' compensation pays medical costs and lost wages for work-related injury and is governed by state statute.
Many commercial contracts also carry specific contractual liability wording and additional insured requirements, and we read those requirements before we market the account. Coverage is written only after underwriting, reflects what the accepting carrier is willing to take on, and takes its final form in the issued policy.
150 N MICHIGAN AVENUE, CHICAGO, IL 60601
Monday - Friday 8am - 4pm